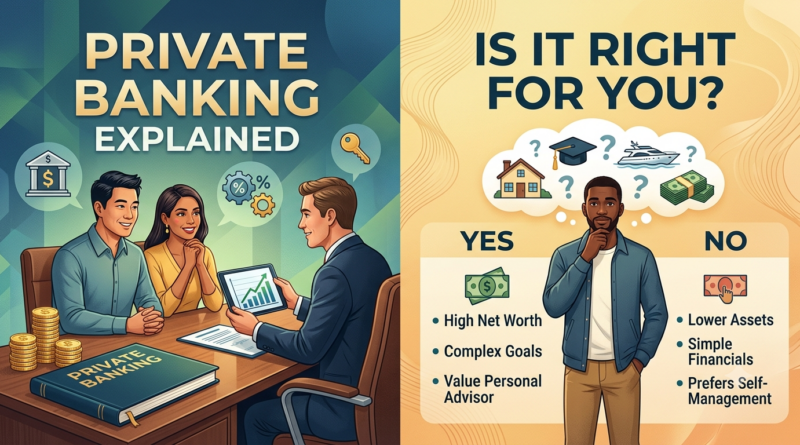
Private Banking Explained: Is It Right for You?
When you start looking into the world of finance, you quickly realize that not all bank accounts are created equal. You have likely heard the term “private bank” in movies or read about it in articles dealing with the ultra-wealthy. But what does it actually mean?
If you are a teenager exploring your financial options, an absolute beginner, or someone wondering how the wealthy handle their cash, getting private banking explained simply can help you understand how the global financial ecosystem operates.
At its core, a private bank doesn’t just mean a building with a vault; it represents a specialized business structure and a suite of high-end financial tools. Let’s break down how these institutions work, what makes them unique, and how they differ from the everyday bank down the street.
1. The Two Meanings of a “Private Bank”
The phrase “private bank” is tricky because the financial world uses it in two completely different ways. To clear up the confusion, we need to look at both definitions.
Meaning A: The Corporate Legal Structure
Historically, a private bank described how a banking business was owned. Instead of being a massive, public corporation owned by thousands of stock market shareholders (like Chase or Barclays), a true private bank is locally owned and operated as a partnership.
In this structure, a small group of partners owns the bank entirely. One famous, long-standing example of this in the United States is Brown Brothers Harriman & Co.
Meaning B: Premium Banking Services for Individuals
In modern times, when people say “private banking,” they are usually talking about premium banking services offered exclusively to wealthy individuals. Most big commercial banks now have a dedicated “private banking” wing inside their company to cater specifically to people with large cash balances.
2. Partnerships vs. Corporations: How Private Banks Are Built
To understand the business side of a private bank, it helps to compare it to a standard corporate bank. The differences in risk and taxes are massive.
[ Corporate Bank ]  ───> Shareholders have Limited Liability (Can only lose what they invest)
[ Private Partnership ] ───> Partners have Unlimited Liability (Personally responsible for all debt)
The Partnership Model (True Private Banks)
Because traditional private banks operate as partnerships rather than corporations, they skip heavy corporate income taxes. The IRS (and equivalent tax bodies in countries like the UK, Canada, and Australia) allows the bank’s profits to pass directly to the individual partners, who then report it on their personal tax returns.
- The Big Catch: The partners face massive risk. They have unlimited liability.
- What is Unlimited Liability? This means that if the bank goes under or loses a lawsuit, the partners are personally responsible for all the bank’s debts. A court can order the partners to sell their personal houses, cars, and assets to pay back the bank’s losses.
The Corporate Model (Standard Commercial Banks)
This is the complete opposite of a public corporation. If you buy a share of stock in a commercial bank, you are a shareholder. You enjoy limited liability—meaning if the bank goes bankrupt tomorrow, the most money you can lose is the exact amount you paid for that single share of stock. The bank’s creditors cannot come after your personal property. However, this structure faces more layers of corporate taxation before any money reaches the owners.
3. Who Gets to Use Private Banking?
Modern private banking isn’t open to just anyone. These institutions function like exclusive clubs, requiring clients to hit strict financial benchmarks to gain access.
To open an account, you must possess a significant amount of liquid assets.
What are Liquid Assets? Think of liquid assets like cash that flows easily, such as money sitting in your checking account or stocks you can sell in five seconds. Non-liquid assets are things like houses or heavy factory machinery—they are worth a lot of money, but you can’t use them to buy groceries today.
The Financial Gates
The minimum entry requirements vary wildly depending on the prestige of the institution:
- Entry-Level Premium Accounts: Some banks allow you to join their premium tiers if you maintain at least $50,000 in cash deposits or investments.
- Elite Private Banks: True elite private banking services typically require a minimum of $500,000 to $1,000,000 in cold, hard cash ready to be deposited.
4. What Specialized Services Do They Offer?
Why do wealthy individuals pay high fees for these accounts instead of using a standard checking account? They do it because they are paying for high-end, customized financial care. When managing high net worth, individuals need specialized tools to protect their money from inflation and taxes.
- Dedicated Financial Advisors: Instead of waiting in line at a branch or calling a generic customer service number, private banking clients get a single, dedicated human advisor. They can text or call this advisor directly to handle any financial task.
- Personalized Estate Planning: Advisors help clients develop complex legal documents, including wills and trusts.
- What is a Trust? Imagine a legal lockbox managed by a trusted third party. A trust outlines exactly how and when your wealth will be handed down to your children or charity, helping your family avoid massive inheritance taxes down the road.
- Custom Credit Solutions: If a private banking client wants to buy a luxury yacht or a commercial building overnight, the bank can quickly spin up a massive, customized loan using the client’s stock portfolio as collateral.
Case Study: Clara’s Business Sale
To see how this works in real life, let’s look at a hypothetical scenario involving a small business owner named Clara.
Clara spent 15 years building a local logistics and delivery company. At age 35, she decided to sell her business to a larger international corporation for $2,000,000 in cash.
[ Clara Sells Business for $2M ] ──> Deposited into Private Bank ──> Dedicated Advisor Assigned
                                                                 ──> 1. Tax Strategy (Saves $150k)
                                                                 ──> 2. L-T Index Funds (Growth)
                                                                 ──> 3. Trust Fund for Kids
Before the sale, Clara used a standard checking account at a local commercial bank. Once the $2,000,000 hit her account, she immediately qualified for her bank’s elite private banking wing.
- The Welcome: The bank assigned her a personal wealth advisor who met with her face-to-face.
- The Strategy: Instead of letting the $2,000,000 sit in a regular account losing value to inflation, her advisor coordinated with tax lawyers to shield her profits legally, saving her $150,000 in unnecessary taxes.
- The Execution: The bank built a diversified portfolio of global investments tailored to her risk comfort level and set up a trust fund to pay for her children’s future college tuition automatically.
Quick Action Checklist
Even if you aren’t ready for elite premium banking services yet, you can use the same mindset to organize your financial basics today:
- [ ] Step 1: Audit your current bank account to see if your bank offers a “tiered” system (many banks offer fee waivers or higher interest if you maintain a balance of $2,000 to $5,000).
- [ ] Step 2: Calculate your total “liquid assets” (add up your cash, savings, and any minor stock investments) so you know your exact starting baseline.
- [ ] Step 3: Draft a basic personal will or medical directive, especially if you have assets like a car or a small business hustle starting to grow.
- [ ] Step 4: Research the difference between limited and unlimited liability if you are thinking about starting a business partnership with a friend.
- [ ] Step 5: Commit to building your savings consistently until you can confidently upgrade your account to capture better banking perks.