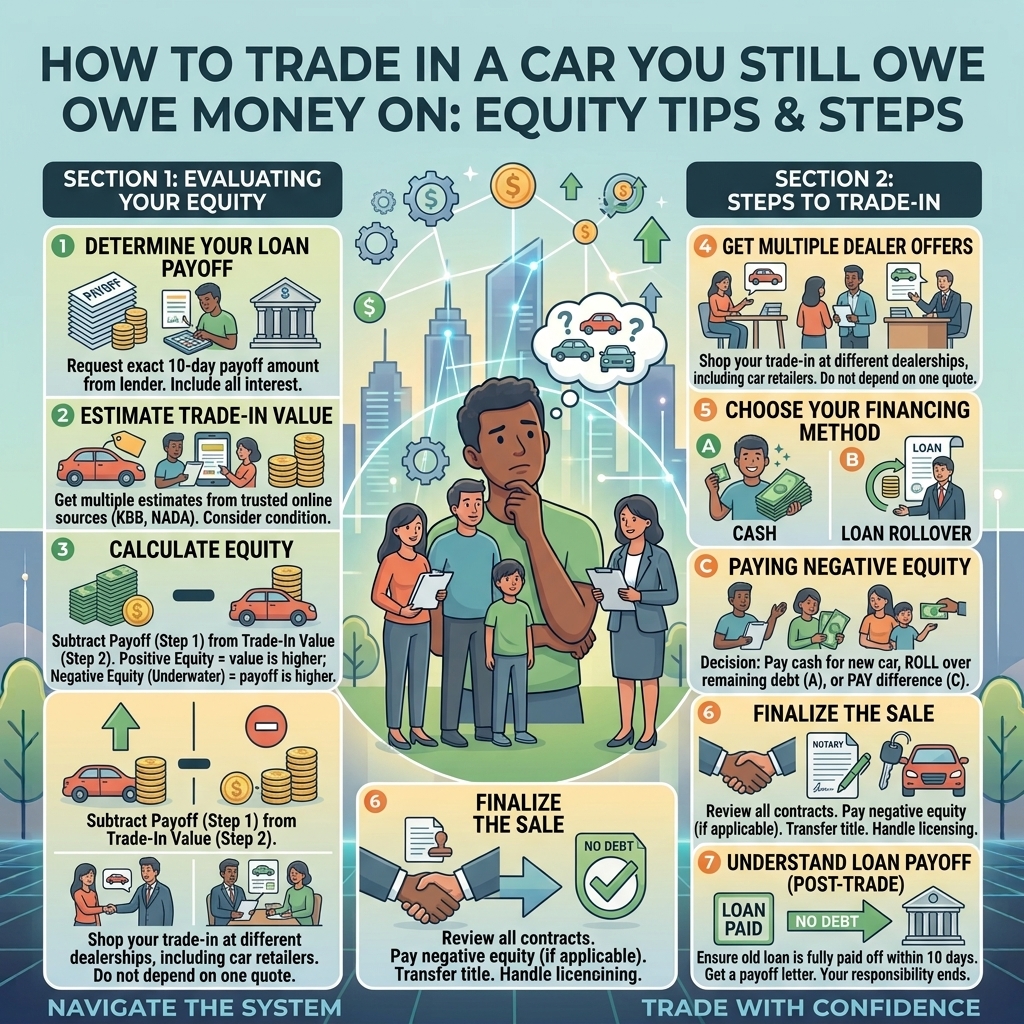
How to Trade In a Car You Still Owe Money On: Equity Tips & Steps
Upgrading to a new vehicle is an exciting step, but trading in your current car when you still have an active auto loan can feel intimidating. The biggest fear for most drivers is whether trading in a financed vehicle is even possible—and if doing so will end up costing a fortune in unexpected fees.
The short answer is yes, you can trade in a car you still owe money on. In fact, dealerships handle this process every day. However, the financial success of your deal depends heavily on your car’s current market value versus your remaining loan balance.
Before visiting a dealership, here is everything you need to know about navigating positive and negative equity, gathering the right paperwork, and avoiding costly financing traps.
Step 1: Determine Your Vehicle’s Equity Position
Before setting foot on a dealership lot, you must calculate your car’s net equity. Equity is simply the difference between what your car is worth on the market and what you owe your lender.
[Current Market Trade-In Value] ─ [Outstanding Loan Payoff Amount] = [Net Equity]
- Positive Equity: Your car is worth more than your remaining loan balance.
- Negative Equity (Being “Upside Down”): Your car is worth less than your remaining loan balance.
How to Calculate Your Numbers
- Contact Your Lender: Request an official 10-day loan payoff amount. This figure includes your remaining principal plus accrued interest.
- Estimate Your Car’s Market Value: Look up your car’s trade-in value on independent valuation sites like Kelley Blue Book (KBB) or Edmunds.
- Get Multiple Dealer Quotes: Never rely on a single dealer’s valuation. Visit two or three local dealerships or online buying services to get competitive appraisal offers.
Trading In With Positive Equity vs. Negative Equity
How your trade-in affects your new purchase depends entirely on which side of the equity line you fall on.
                         [Calculate Your Equity Position]
                                        │
                 ┌──────────────────────┴──────────────────────┐
          POSITIVE EQUITY                               NEGATIVE EQUITY
   (Car Value > Loan Balance)                    (Car Value < Loan Balance)
                 │                                             │
   ┌───────────────────────────┐                 ┌───────────────────────────┐
   │ Use remaining balance     │                 │ Choose a Mitigation Path: │
   │ as a down payment toward  │                 ├───────────────────────────┤
   │ your new vehicle purchase.│                 │ 1. Pay difference in cash.│
   └───────────────────────────┘                 │ 2. Downgrade vehicle model│
                                                 │ 3. Hold car until loan    │
                                                 │    balance drops.         │
                                                 └───────────────────────────┘
Scenario A: Trading In With Positive Equity (The Ideal Situation)
If your car is valued at $9,000 and your remaining loan payoff is $6,000, you have $3,000 in positive equity.
When you trade the car in, the dealer pays off your $6,000 loan to the bank, acquiring the title. The remaining $3,000 credit is applied directly as a down payment toward your new vehicle, lowering the total amount you need to borrow.
Scenario B: Trading In With Negative Equity (The Financial Trap)
If your car is valued at $8,000 but your loan payoff is $9,000, you have $1,000 in negative equity.
To complete the trade, that $1,000 gap must be covered. Dealers often offer to “roll” this negative equity into your new car loan. Avoid this trap whenever possible. Rolling old debt into a new auto loan increases your monthly payments, causes you to pay interest on debt for a car you no longer own, and instantly puts you upside down on your new vehicle.
4 Smart Strategies for Handling Negative Equity
If you owe more than your car is worth but still need to change vehicles, consider these practical options to protect your finances:
| Strategy | How It Works | Financial Impact |
| Pay the Difference Out-of-Pocket | Pay the negative equity gap in cash at the time of trade-in. | Clears old debt immediately; prevents interest from compounding on your new loan. |
| Downgrade to an Inexpensive Model | Trade into a lower-tier model or a reliable used vehicle rather than an expensive new car. | Reduces your total loan footprint and keeps monthly payments manageable. |
| Sell to a Private Buyer | Sell your car directly to an individual buyer instead of trading it to a dealer. | Private buyers pay closer to retail value than wholesale dealer trade-in rates, reducing your equity gap. |
| Wait Out the Depreciation Curve | Keep driving your current car until regular monthly payments bring your loan balance below the market value. | Vehicles experience the heaviest depreciation (up to 20%) in their first year; holding past year 2 or 3 stabilizes equity. |
What Paperwork Do You Need at the Dealership?
To ensure a smooth trade-in process and prevent dealer lowballing, bring the following items with you:
1.Loan Account & Payoff Information:Required for payoff verification.
Bring your lender’s name, your loan account number, and the official 10-day payoff statement printout.
2.Government-Issued Driver’s License:Required for legal identity verification.
Ensures the dealership can legally register the new vehicle and transfer title ownership.
3.Current Vehicle Registration & Title:Required for ownership transfer.
If the vehicle is financed, bring your current state registration document.
4.Proof of Auto Insurance:Required to drive off the lot.
Bring your current insurance card or policy documentation to transfer coverage to the new car.
5.Third-Party Value Printouts:Required for price negotiations.
Bring printed trade-in estimates from KBB, Edmunds, or competitor quotes to negotiate a fair trade value.
6.All Keys, Fobs, and Remotes:Required for full vehicle transfer.
Missing key fobs can reduce your trade-in offer by $150–$400 per missing key.
Alternative Option: Private Sale vs. Dealer Trade-In
Trading in at a dealership is convenient because the dealer manages the title transfer and loan payoff paperwork for you. However, you pay for that convenience in lower trade offer values.
Selling your car to a private buyer eliminates the dealership middleman, allowing you to secure a higher sale price.
[Private Buyer pays total agreed price to Lender] ──> [Lender releases title & pays excess cash to You]
- If Selling Privately with Positive Equity: The buyer pays the agreed purchase price directly to your lender. The lender pays off your loan, sends the vehicle title to the buyer, and mails you a check for the remaining positive equity balance.
- If Selling Privately with Negative Equity: You must bring cash to the closing bank transaction to pay the lender the difference between the buyer’s purchase price and your total loan payoff amount.
Frequently Asked Questions
When is the best time of year to trade in a car?
The first two quarters of the year (January through June) are generally best for trade-in values, as consumer demand is higher. Furthermore, trading in a car before it hits the 5-year mark yields better returns, as vehicle depreciation rates accelerate again after year five.
Can I trade in a car that has mechanical issues or minor damage?
Yes. Minor cosmetic flaws like small door dings or minor scratches will not significantly impact your offer. However, major mechanical issues (engine or transmission problems) will noticeably reduce your vehicle’s trade-in value, as dealers will deduct their estimated reconditioning costs from your offer.
When is the best time to buy a used car?
The last quarter of the year (October through December) is the best time to buy a used vehicle. Dealerships receive a high volume of trade-ins during the holiday season and are eager to meet year-end sales quotas, making them more willing to negotiate discount prices.
Quick Action Checklist
- [ ] Get Your 10-Day Loan Payoff: Call your auto lender to get your exact payoff figure and account details.
- [ ] Run Market Valuations: Check trade-in values on Kelley Blue Book and Edmunds using your exact mileage and vehicle condition.
- [ ] Calculate Your Net Equity: Subtract your loan payoff amount from your estimated market trade-in value.
- [ ] Gather Required Documents: Collect your registration, driver’s license, insurance proof, payoff sheet, and all sets of keys.
- [ ] Set Loan Term Limits: If financing a new car, cap your loan length at a maximum of 60 months for new vehicles or 36 months for used vehicles to prevent future negative equity.
Disclaimer: The content on this website is for informational and educational purposes only and should not be construed as professional financial, investment, tax, or legal advice. I am not a licensed financial advisor. While I strive to keep the information accurate and up to date, financial markets and laws change frequently. Always consult with a qualified financial professional before making any financial or investment decisions based on the information provided on this site.