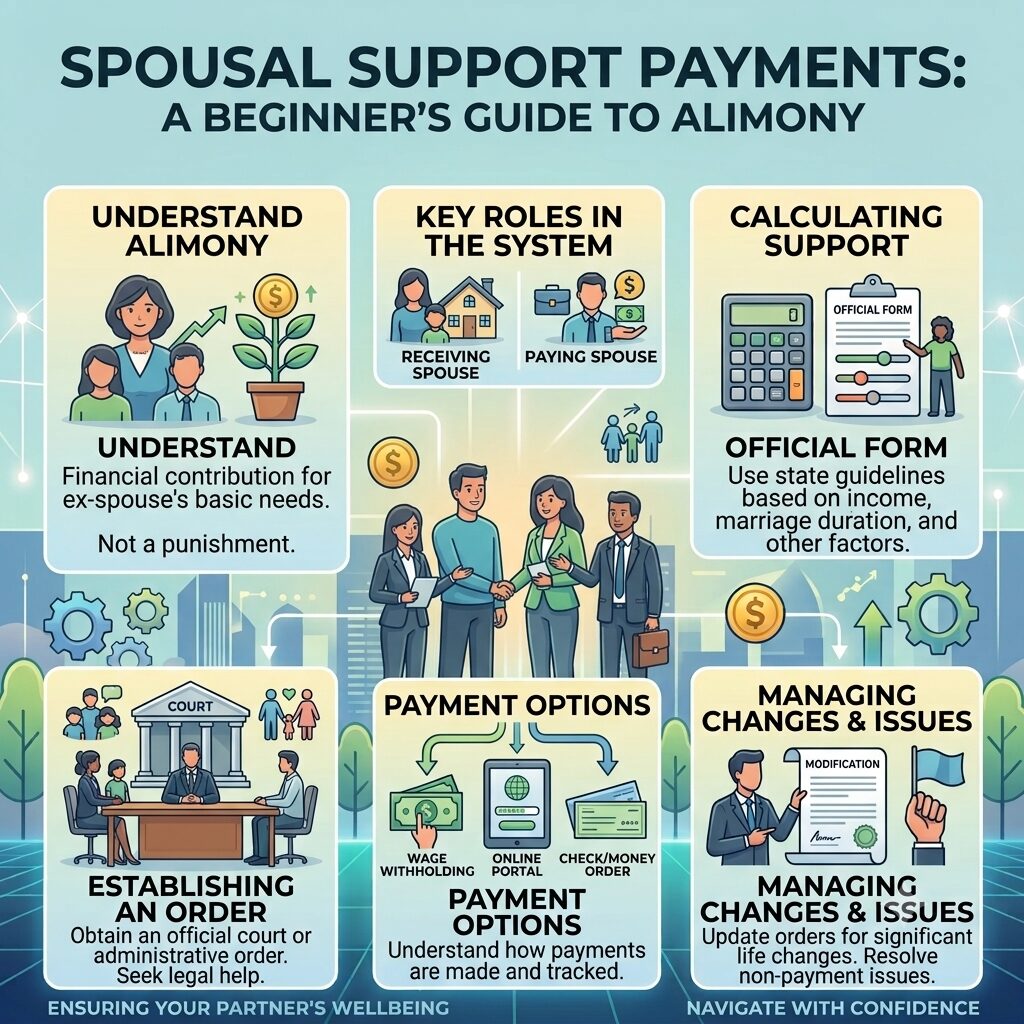
Spousal Support Payments: A Beginner’s Guide to Alimony
Splitting up with a partner is never easy, but when you add money to the mix, things can get incredibly complicated. One of the most common areas where divorced couples run into massive conflict is over spousal support payments, which are also frequently called alimony.
If one partner earned much more than the other during the relationship, the legal system often steps in to balance the scales. Whether you are the person who needs financial help to get back on your feet, or the person who is being asked to pay, understanding how these payments work is crucial. By empowering yourself with clear information and personal budgeting strategies, you can reduce the stress of alimony disputes and protect your financial independence.
What are Spousal Support Payments?
At its core, spousal support is a regular cash transfer paid by one former partner to another after a marriage ends.
The Purpose of Support: The goal of alimony is to help the lower-earning partner cover their necessary monthly expenses and bills while they transition to single life. It is designed to ensure that a person doesn’t face sudden poverty simply because a relationship ended, especially if they put their career on hold to look after a family.
Many people assume that if their relationship breaks down, they immediately need to hire an expensive lawyer to fight it out in court. However, letting a stranger—like a family court judge—decide your financial future is incredibly risky and expensive. Whenever possible, trying to discuss your finances openly in advance can save you thousands of dollars that could be used to fund your new life instead.
Tracking Your Monthly Expenses: The Basis of Every Plan
Whether you plan to settle your finances privately or through a legal professional, you cannot make smart choices without real numbers. You need a crystal-clear look at your cash flow.
Both partners should establish clear accounting practices. Fortunately, this does not require a degree in finance. Modern digital banking apps allow you to print out detailed spending reports and categorize your outgoings in seconds. You need to map out exactly what it costs to live each month by dividing your expenses into two main buckets:
1. Fixed Expenses (The Non-Negotiables)
These are bills that cost the exact same amount every single month. They form the absolute baseline of what you need to survive.
- Rent or mortgage payments.
- Car loans and vehicle insurance.
- Property taxes and local utility rates.
2. Variable Expenses (The Flexible Costs)
These are day-to-day costs that change depending on your habits and needs.
- Groceries and household supplies.
- Fuel, public transit fares, and travel.
- Clothing, medical costs, and personal care.
Global Framework: How Alimony Changes Around the World
While the core concept of supporting a former partner exists globally, different countries use unique terminology and rules to decide who pays what.
- United States: The rules vary dramatically depending on your state. Some states offer temporary “rehabilitative” alimony to help a spouse train for a new job, while others still offer long-term support for marriages that lasted over ten or twenty years.
- United Kingdom: Formally called “Spousal Maintenance.” Courts rarely grant this for life anymore. Instead, they prefer a “clean break” approach or award maintenance for a fixed number of years to give the receiving partner time to become self-sufficient.
- Canada: Governed by the Spousal Support Advisory Guidelines (SSAG). The system uses complex math formulas based on the length of the marriage, age of the partners, and gross incomes to suggest a specific range of dollar amounts.
- Australia: Known as “Spousal Maintenance.” Under the Family Law Act, a person only has a duty to support their ex-partner if the applicant cannot adequately support themselves and the other person has the capacity to pay. It is viewed as a temporary stepping stone rather than a permanent income.
Step-by-Step Guide: What to Do During a Support Crisis
If your income suddenly drops because you lost your job or faced a medical emergency, you might find yourself completely unable to afford your mandatory spousal support payments. If you hit a financial wall, you must follow a proactive path to avoid ruining your credit rating or facing legal penalties.
1.Gather Income Documentation:Print your reports.
Collect physical proof of your financial change immediately, such as a redundancy note, tax records, or medical files.
2.Contact Your Creditors:Call your banks.
Reach out to the institutions holding your car loans or mortgage. Explain your situation and set up temporary payment plans. Showing the court you are actively managing your debt counts heavily in your favor.
3.File for a Modification:Request an official shift.
Do not just stop paying. Petition the family court or your local authority for a formal reduction in support based on your new income reality.
Case Studies: Two Paths to Handling Alimony
Let’s look at how two different couples managed their alimony disputes during a split.
Scenario A: Tom and Elena’s Collaborative Success
Tom and Elena decided to separate after fifteen years. Elena had stayed home to raise their children, meaning Tom was the primary earner.
- The Action: Instead of hiring aggressive lawyers right away, they sat down with a neutral family accountant. They printed out their online banking statements to build a shared map of their regular monthly expenses.
- The Result: Because they used real data, they agreed on a fair, time-limited spousal support plan that covered Elena’s rent and university courses while she re-entered the workforce. They avoided a bitter court battle, saved thousands in legal fees, and protected their shared assets.
Scenario B: Rachel and Mark’s Communication Breakdown
Rachel and Mark suffered a total breakdown in communication. When Mark’s business experienced a massive financial drop, he simply stopped sending his agreed support payments without telling Rachel.
- The Action: Mark ignored Rachel’s calls and did not file for a court modification because he thought the system was unfair. Rachel, unable to pay the mortgage on her own, had to hire a family law attorney to handle the communication.
- The Result: Because Mark cut off contact, the court found him in default. His wages were garnished, and his credit rating was severely damaged due to missed payments. The legal fees for both sides ended up costing more than the support money they were arguing about.
Pro-Tips for Managing Spousal Support
- Utilize Free Mediation Options: If you cannot talk to your ex-partner directly without arguing, do not rush to court. Look into neutral third parties like a trusted family friend, a professional accountant, or community mediation services. These options are far cheaper than standard court battles.
- Build an Independent Budget: The moment a split looks likely, create a brand-new personal budgeting plan based entirely on a single income. Cut out all non-essential luxury items to build a cash cushion.
- Understand Tax Implications: In many regions, the tax rules around alimony have changed. Always check with a local accountant to see if your support payments are tax-deductible or if the person receiving them has to pay income tax on the funds.
Common Pitfalls to Avoid
Allowing Emotions to Drive Financial Decisions
Divorce is incredibly painful, and it is easy to let anger guide your actions. Trying to inflate your monthly expenses to punish your ex-partner, or withholding support money out of spite, will always backfire. Courts respond to cold, hard numbers—not emotional games. Keep your financial records transparent and completely honest.
Letting Properties Face Foreclosure
If you and your partner are locked in a dispute over who pays the mortgage or the car note, do not just leave the bills unpaid. If a car gets repossessed or a home goes into foreclosure, both of your credit files will be ruined for years. Work together to keep accounts current, or agree to sell the asset quickly to protect your financial health.
Quick Action Checklist
- [ ] Log Your Spending: Download your last six months of bank statements and group them into fixed and variable costs.
- [ ] Check Local Guidelines: Search your local government or state website for their official spousal support calculation formula to find your benchmark numbers.
- [ ] Consult a Neutral Professional: Schedule an initial session with a family mediator or accountant before hiring an aggressive trial attorney.
- [ ] Review Joint Debt Agreements: Make a comprehensive list of all shared loans, and contact creditors to discuss how to separate your names from the accounts.
Disclaimer: The content on this website is for informational and educational purposes only and should not be construed as professional financial, investment, tax, or legal advice. I am not a licensed financial advisor. While I strive to keep the information accurate and up to date, financial markets and laws change frequently. Always consult with a qualified financial professional before making any financial or investment decisions based on the information provided on this site.