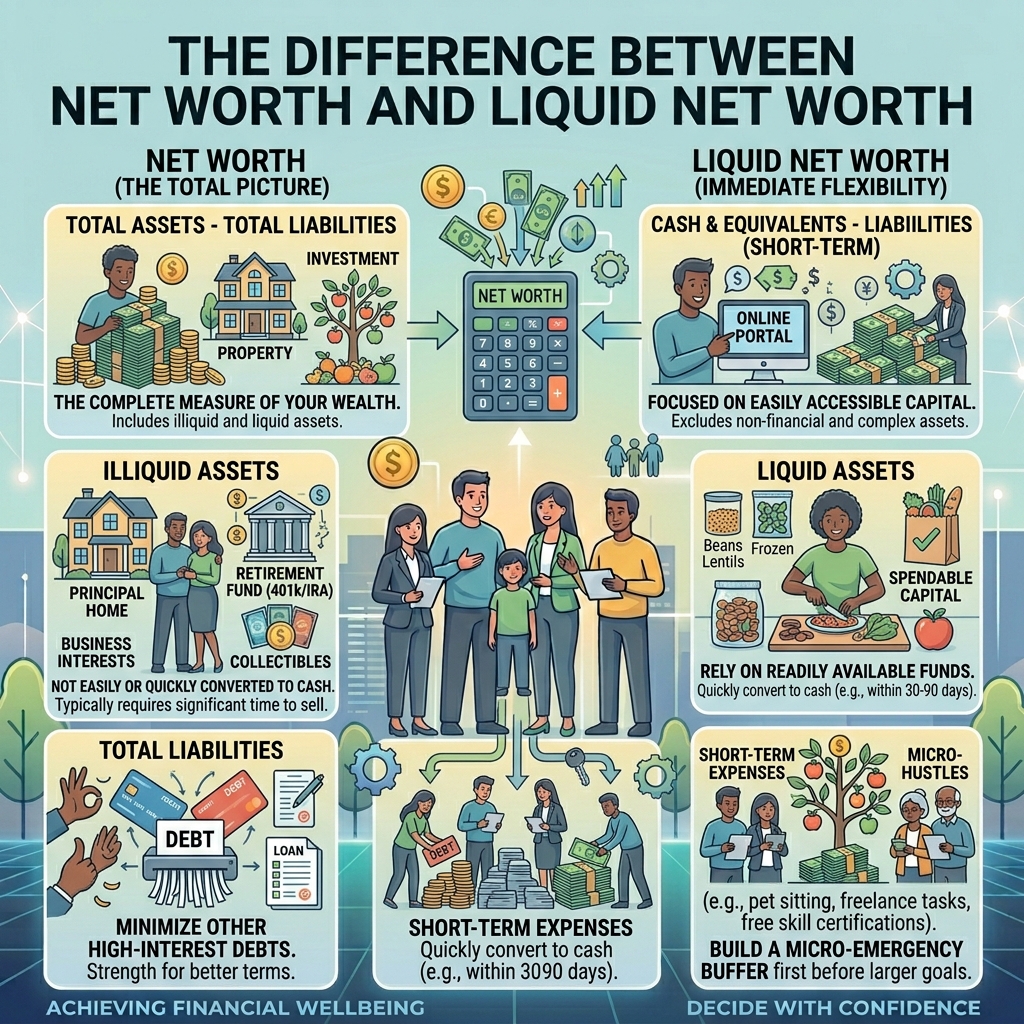
The Difference Between Net Worth And Liquid Net Worth
If you have ever looked up a public figure’s financial status online, you have likely seen a single number listed as their “net worth.” However, that headline figure rarely tells the whole story.
A far more accurate picture of someone’s financial health emerges when you compare their net worth against their liquid net worth.
For example, owning a $2 million primary residence or commercial property looks impressive on paper. However, real estate is an illiquid asset—you cannot instantly use it to buy groceries or pay emergency bills. Selling property at full market value can take months or even years.
Understanding the distinction between total net worth and liquid net worth is essential for your personal finances. Here is a clear breakdown of how both metrics work globally, how to calculate them, and how to build lasting financial security.
What Is Net Worth?
At its core, net worth is a straightforward mathematical snapshot of your entire financial life:
[Total Value of Everything You Own (Assets)] ─ [Total Money You Owe (Liabilities)] = [Net Worth]
1. Assets (What You Own)
This includes non-liquid physical property (such as real estate, vehicles, art, and collectibles) alongside liquid cash, bank balances, stock portfolios, and government- or employer-sponsored retirement plans (such as 401(k)s in the US, ISAs/Pensions in the UK, RRSPs in Canada, or Superannuation in Australia).
2. Liabilities (What You Owe)
This includes all outstanding debt balances, such as home mortgages, vehicle loans, credit card balances, personal loans, and university student debt.
Note for Beginners: If you are a recent university graduate or just starting your career, your net worth may be zero or negative due to initial student debt or starting loans. This is entirely normal. The goal of financial planning is to gradually acquire appreciating assets while paying down debt over time.
What Is Liquid Net Worth?
Liquid net worth measures only the assets you can convert into cash almost immediately at full market value, minus your total liabilities.
[Total Cash & Cash-Equivalent Assets] ─ [Total Liabilities] = [Liquid Net Worth]
What Counts as a Liquid Asset?
- Physical cash currency and everyday checking/current account balances.
- High-yield savings accounts and short-term money market accounts.
- Dedicated emergency cash funds.
- Publicly traded stocks, bonds, and exchange-traded funds (ETFs) in standard brokerage accounts that can be liquidated within days.
What Is Excluded (Illiquid Assets)?
Major physical assets—like real estate, vehicles, private business equity, and heavy machinery—are excluded because selling them quickly usually requires accepting a heavy discount.
Furthermore, tax-advantaged retirement accounts (such as a 401(k), IRA, or Superannuation) are generally treated as illiquid for short-term needs because accessing them prior to official retirement age triggers steep government penalties and income tax charges.
Step-by-Step Calculation Comparison
To see how these two metrics differ, consider this realistic financial scenario:
Sample Asset & Liability Ledger
- Primary Residence Value: $250,000
- Vehicle Current Value: $15,000
- Cash & Everyday Bank Accounts: $6,500
- High-Yield Savings & Emergency Fund: $18,000
- Certificates of Deposit / Fixed Term Deposits: $10,000
- Publicly Traded Stock Portfolio: $20,000
- Total Assets:$319,500
- Outstanding Home Mortgage Balance: $150,000
- Auto Loan Balance: $5,000
- Student Loan Balance: $7,000
- Credit Card Balance: $2,000
- Total Liabilities:$164,000
Calculation 1: Total Net Worth
| Category | Total Value |
| All Combined Assets | $319,500 |
| Less: All Liabilities | – $164,000 |
| TOTAL NET WORTH | = $155,500 |
This positive figure reflects a healthy overall financial position built on property equity and investments.
Calculation 2: Strict Liquid Net Worth
To calculate strict liquid net worth, remove illiquid physical assets (the $250,000 house and $15,000 vehicle) while keeping all debt obligations:
| Category | Total Value |
| Liquid Assets Only (Cash, Savings, Stocks, Term Deposits) | $54,500 |
| Less: All Liabilities (Mortgage, Auto, Student Debt, Cards) | – $164,000 |
| STRICT LIQUID NET WORTH | = – $109,500 |
The “20% Discount Rule” Alternative: If you must factor physical assets into a short-term liquidity estimate, financial analysts often subtract 20% off market valuations to account for forced quick-sale losses and closing fees.
Why Liquid Net Worth Matters for Global Investors
Having a high total net worth feels great, but liquid net worth is what protects you during economic downturns, sudden job losses, or health crises.
                  [Facing an Unexpected Financial Crisis?]
                                     │
         ┌───────────────────────────┴───────────────────────────┐
   HIGH LIQUIDITY                                          LOW LIQUIDITY
   (Cash reserves & flexible stocks)                       (Wealth locked in real estate)
         │                                                       │
   • Covers living costs directly                          • Forced to take high-cost loans
   • Avoids forced asset fire-sales                        • Risk of property foreclosure
   • Keeps long-term plans intact                          • High risk of debt compounding
During global economic shocks, access to immediate liquidity prevents you from being forced to sell real estate at a loss or take on predatory, high-interest debt to cover daily living expenses.
4 Practical Steps to Increase Your Net Worth
1.1. Pay Yourself First: Automate your cash flow.
Set up automatic transfers on payday to send 10% to 20% of your net income directly into savings and investment accounts before spending on discretionary items.
2.2. Eliminate Toxic Consumer Debt: Target high-interest balances.
Prioritize paying off high-interest credit card debt and unsecured loans using the debt avalanche or snowball method. Eliminating interest payments directly increases your net worth.
3.3. Invest for Long-Term Growth: Utilize low-cost index funds.
Regularly invest spare capital into broad global index funds (ETFs). Over time, market growth and compound interest build both asset value and portfolio liquidity.
4.4. Build a 3-to-6-Month Cash Safety Net: Maintain a dedicated buffer.
Keep 3 to 6 months of essential living costs in a high-yield savings account. This protects your long-term illiquid assets from being sold off during emergency situations.
Frequently Asked Questions
Is a 401(k) or pension account considered a liquid asset?
No. While retirement accounts (such as 401(k)s in the US, ISAs/pensions in the UK, or Superannuation in Australia) contribute significantly to your overall net worth, they are not considered liquid assets. Early withdrawals prior to retirement age usually incur statutory tax penalties and government fees.
What is a good net worth target by age?
Net worth targets vary widely depending on local cost of living and career paths. Generally, benchmarks suggest having an overall net worth equal to 1x your annual salary by age 30, 3x by age 40, and 6x by age 50.
Quick Action Checklist
- [ ] List Your Assets: Record the current value of your bank balances, investment accounts, home, and vehicles.
- [ ] List Your Liabilities: Record all current balances on mortgages, car loans, credit cards, and student loans.
- [ ] Calculate Both Figures: Subtract liabilities from total assets for your Net Worth, and subtract liabilities from cash/stock assets for your Liquid Net Worth.
- [ ] Optimize Emergency Liquidity: Ensure at least 3 to 6 months of essential expenses reside in liquid, penalty-free savings accounts.
Disclaimer: The content on this website is for informational and educational purposes only and should not be construed as professional financial, investment, tax, or legal advice. I am not a licensed financial advisor. While I strive to keep the information accurate and up to date, financial markets and laws change frequently. Always consult with a qualified financial professional before making any financial or investment decisions based on the information provided on this site.