Smart Ways to Spend 500 Dollars: What to Do with Unexpected Cash
Few things feel better than an unexpected cash windfall. Maybe it is an invoice you completely forgot about, a larger tax refund than you expected, a gift from family, or a bonus at work.
Unexpected cash feels like “free money.” Because you didn’t budget for it, it can be tempting to spend it instantly on a weekend trip or a shopping spree. But blowing a lump sum without a plan is one of the most common money mistakes beginners make.
The Golden Rule of Personal Finance: Tell your money where to go before you spend it. Unexpected cash is a golden opportunity to make your assets work for you, build financial security, and upgrade your life.
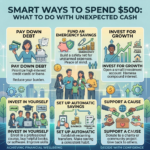
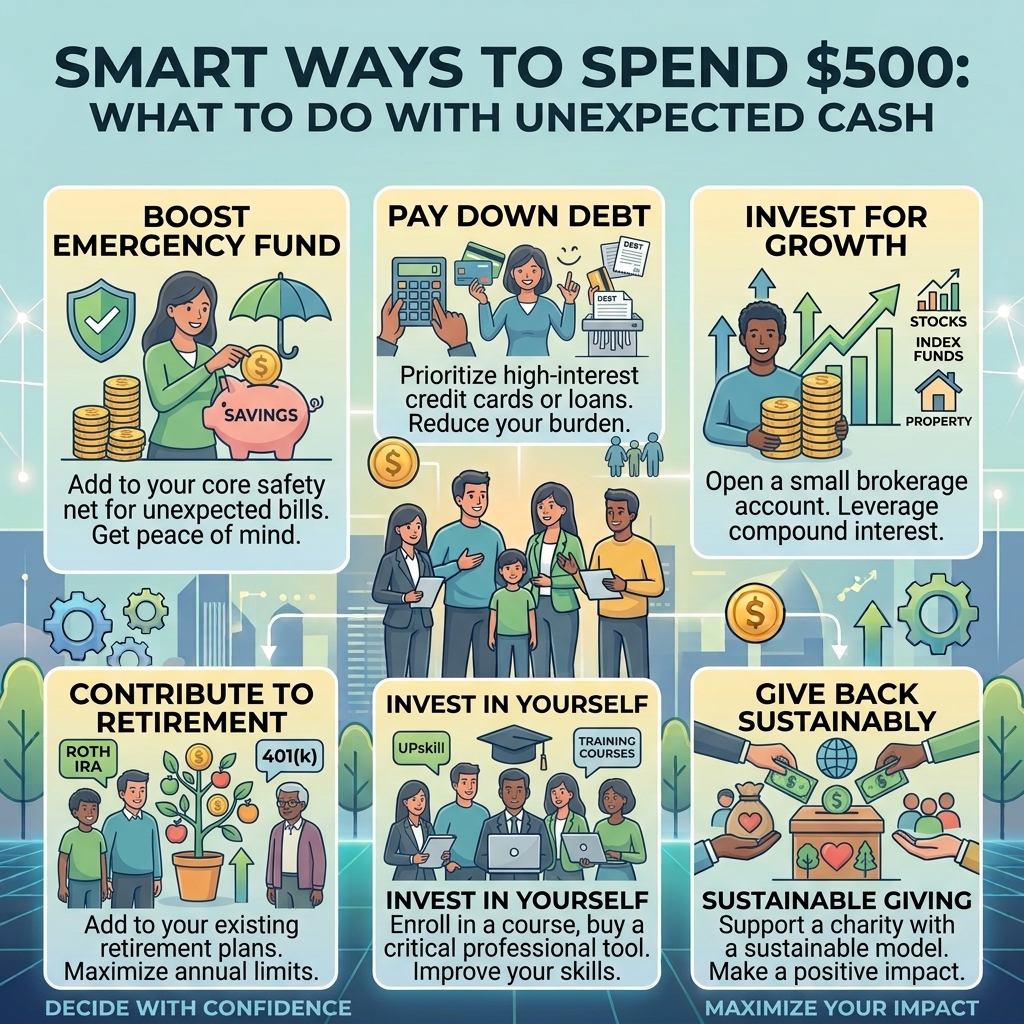
If you just landed an extra $500, here are the smartest, most impactful ways to put that money to work today across four key areas: Building Wealth, Securing Your Future, Upgrading Yourself, and Protecting Your Assets.
1. Build Financial Security & Debt Freedom
Build or Boost Your Emergency Fund
If you do not have an emergency fund yet, stop right here: your extra $500 should become your very first installment. An emergency fund is a cash safety net held in a liquid bank account that you touch only for unexpected life events—like urgent medical bills, car breakdowns, or sudden job loss. Having a cash cushion means that the next time life throws a curveball, you won’t need to rely on high-interest credit cards.
| Goal Phase | Target Amount | What It Covers |
| Starter Fund | $500 – $1,000 | Minor surprises (car repairs, urgent travel) |
| Full Emergency Fund | 3 to 6 months of living expenses | Major shocks (job loss, prolonged illness) |
Consolidate or Crush High-Interest Debt
Putting $500 directly toward credit cards or high-interest loans gives you an instant, guaranteed return on your investment. While $500 might not erase a massive loan entirely, it can easily wipe out a smaller store card balance or significantly reduce the overall interest you pay every month.
Prepay Rent or Mortgage Installments
Imagine paying one extra mortgage or rent installment in advance. It puts you a full month ahead of your expenses. If an unexpected job loss or income disruption occurs, knowing your housing costs are covered for the upcoming month offers immense mental peace and breathing room.
2. Invest in the Markets & Your Future
Start Micro-Investing in Stock Market ETFs
You do not need thousands of dollars to start investing. If you have never invested before, placing your money into an Exchange-Traded Fund (ETF) is one of the safest ways to enter the market. An ETF bundles hundreds of individual stocks into a single fund.
Instead of betting your entire $500 on one risky company, low-cost ETFs—such as those following the S&P 500 index offered by major providers like Vanguard (VOO), iShares (IVV), or SPDR (SPY)—spread your money across top market performers with low fees.
Fund Your Retirement Early
Thanks to compound interest—where your earnings generate their own earnings over time—a single $500 contribution in your 20s or 30s can grow into thousands by the time you stop working. Consider contributing to a tax-advantaged account like a Roth IRA or your employer-sponsored 401(k) (especially if your company offers a matching contribution).
Explore High-Risk Alternative Assets (With Caution)
If your emergency fund is fully funded and you have no high-interest debt, you might allocate a small portion of unexpected cash toward higher-risk assets like cryptocurrencies (e.g., Bitcoin or Ethereum). However, treat speculative assets as high-risk ventures: never invest money you cannot afford to lose.
Seed an Education Savings Account
If you have children or plan to in the future, starting an education fund (like a 529 Plan) with an unexpected $500 gives them a head start. By starting early, that initial deposit has years to grow tax-free, helping reduce future student loan burdens.
3. Upgrade Your Health, Career & Wellbeing
1.Kickstart Career Upgrades:Boost your primary income potential.
Use $500 to earn an industry-recognized certification or attend a specialized workshop. If a $500 course helps you negotiate a raise or secure a promotion, that initial deposit pays for itself many times over.
2.Get a Preventative Health Screening:Prevent expensive future medical bills.
No amount of money can buy good health. Using your cash windfall for comprehensive dental checkups, routine eye exams, or a full health screening can catch potential issues early before they turn into costly medical emergencies.
3.Secure Term Life Insurance:Protect your dependents’ lifestyle.
If you have dependents, allocating $500 toward an annual term life insurance premium ensures your family’s standard of living remains safe and stable no matter what happens.
4. Protect Your Physical Assets & Reduce Monthly Bills
Perform Essential Vehicle Maintenance
New cars are expensive, and ignoring routine maintenance on an existing vehicle leads to catastrophic repair bills down the road. Spending $500 on new tires, brake service, or fluid changes keeps your vehicle running reliably and avoids much larger expenses later.
Make Energy-Efficient Home Improvements
While $500 won’t cover a full kitchen remodel, it can fund high-ROI minor home repairs. Upgrading to a smart thermostat, sealing drafty doors and windows, or replacing leaking plumbing fixtures can lower your monthly utility bills, easily saving you hundreds of dollars every year.
Case Studies: Two Ways to Handle a $500 Windfall
Scenario A: Maya’s High-Yield Plan
Maya received an unexpected $500 tax refund. Instead of leaving it in her checking account where it would slowly disappear on dining out and online shopping, she split the money intentionally.
- The Action: Maya put $300 into a high-yield emergency savings app and used the remaining $200 to enroll in a digital project management certification course.
- The Result: Six months later, Maya used her new certification to secure a promotion at work, increasing her monthly salary by $350 while keeping her $300 emergency safety net intact.
Scenario B: Sam’s Impulse Spend
Sam received the same $500 tax refund and spent it immediately on designer clothes and a weekend night out.
- The Action: Sam enjoyed the weekend, but two weeks later, his car’s alternator failed, resulting in an urgent $450 repair bill.
- The Result: Because Sam had no emergency savings, he had to charge the $450 repair to a high-interest credit card. He ended up paying high interest charges on that repair for over a year.
Pro-Tips for Managing Financial Windfalls
- Follow the 80/20 Rule: You do not have to be completely rigid. A balanced strategy for unexpected cash is to put 80% ($400) toward responsible goals (debt, savings, investing) and use 20% ($100) for a guilt-free reward. This protects your financial future while still letting you celebrate.
- Automate Your Decisions Immediately: The longer unexpected cash sits in your everyday spending account, the higher the chance you will spend it on small, forgettable daily purchases. Move the money to its intended destination the day you receive it.
- Avoid the “Free Money” Trap: In psychology, “mental accounting” causes people to treat found money with less care than paycheck income. Remember: a dollar of unexpected cash has the exact same purchasing power as a dollar you worked 40 hours to earn.
Frequently Asked Questions
How can I start investing with little to no money?
You can start investing with as little as $5 to $50 using micro-investing apps, fractional shares, or low-minimum index funds. Many platforms allow you to set up small, automated monthly contributions so your portfolio grows quietly over time.
How do I decide whether to pay off debt or save my $500?
Look at the interest rate on your debt. If you are carrying high-interest credit card debt (typically above 8%–10% interest), paying down that balance yields a higher financial return than most standard savings accounts. However, if you have zero cash reserves, prioritize building a small $500 starter emergency fund first.
Quick Action Checklist
- [ ] Audit Your Safety Net: If you have less than $1,000 in liquid savings, send your $500 straight to a high-yield emergency savings account.
- [ ] Target High-Interest Debt: If your emergency fund is secure, apply the balance toward your highest-interest credit card.
- [ ] Apply the 80/20 Split: Set aside $400 for long-term investments or savings, and use $100 for a small, intentional reward.
Disclaimer: The content on this website is for informational and educational purposes only and should not be construed as professional financial, investment, tax, or legal advice. I am not a licensed financial advisor. While I strive to keep the information accurate and up to date, financial markets and laws change frequently. Always consult with a qualified financial professional before making any financial or investment decisions based on the information provided on this site.